The most effective way to teach your child the value of money is to stop treating allowance as an unconditional reward and start treating it as a tool for developing a growth mindset. By shifting from a “gift” model to a “contribution-based” model, you provide the structure necessary for your child to understand that resources are earned through effort, planning, and persistence rather than simply appearing on demand.
- Decouple allowance from basic chores: Basic household contributions should be expected as a member of the family, while “growth-mindset” tasks are optional ways to earn extra funds.
- Implement the 3-Jar System: Force intentional decision-making by splitting every dollar into ‘Spend,’ ‘Save,’ and ‘Give’ categories to prevent impulsive consumption.
- Focus on the process, not the outcome: Use the allowance system to reward the effort of learning a new skill or overcoming a challenge, rather than just the successful completion of a task.
Why the Traditional Allowance Model Often Fails
For many parents in their 30s and 40s, the default approach to allowance is simple: you give your child a set amount of money each week or month in exchange for them doing their chores. While this seems logical, it often backfires. When money is tied directly to routine tasks like making the bed or clearing the dinner table, you inadvertently send the message that being a contributing member of the family is a commercial transaction.
If you pay your child to keep their room clean, what happens when they decide they don’t want the money? They stop cleaning their room. This transforms a responsibility into a negotiation. A growth-mindset allowance system, by contrast, separates the “base” expected contributions from “growth-oriented” challenges. This distinction is vital for teaching children that they have a duty to their community (the family) regardless of pay, and that additional rewards come from pushing their personal boundaries.
Consider the psychological impact: when a child earns money through a growth-mindset task—such as learning to code a basic program, practicing an instrument for an extra hour, or organizing a complex project—they associate the money with the effort and the struggle. This is the foundation of financial literacy: understanding that money is a byproduct of value creation, not a passive entitlement.
Defining the ‘Growth-Mindset’ Framework
A growth-mindset allowance isn’t about paying for grades or basic chores. It is about incentivizing the pursuit of difficulty. In Carol Dweck’s research on growth mindset, the core premise is that intelligence and ability can be developed through dedication and hard work. When applying this to money, the goal is to reward the process of improvement.
Here is how you can structure the system effectively:
| Task Type | Definition | Financial Treatment |
|---|---|---|
| Core Contributions | Basic family responsibilities (e.g., setting the table, pet care). | No monetary reward. Expected as part of being in a family. |
| Growth Tasks | Tasks that require learning a new skill or significant effort. | Paid at a rate agreed upon in advance based on complexity. |
| Fixed Stipend | A small, consistent base amount for managing regular expenses. | Used for practicing long-term saving and budgeting. |
The “Growth Task” is the most important element here. If your child wants to earn extra money, they must propose a task that stretches their current abilities. For example, rather than paying them to “wash the car,” you might pay them to “research the best cleaning products, create a schedule, and execute the wash using a new technique.” You aren’t paying for the car wash; you are paying for the executive function and the learning process.
Implementation: The 3-Jar System for Financial Discipline
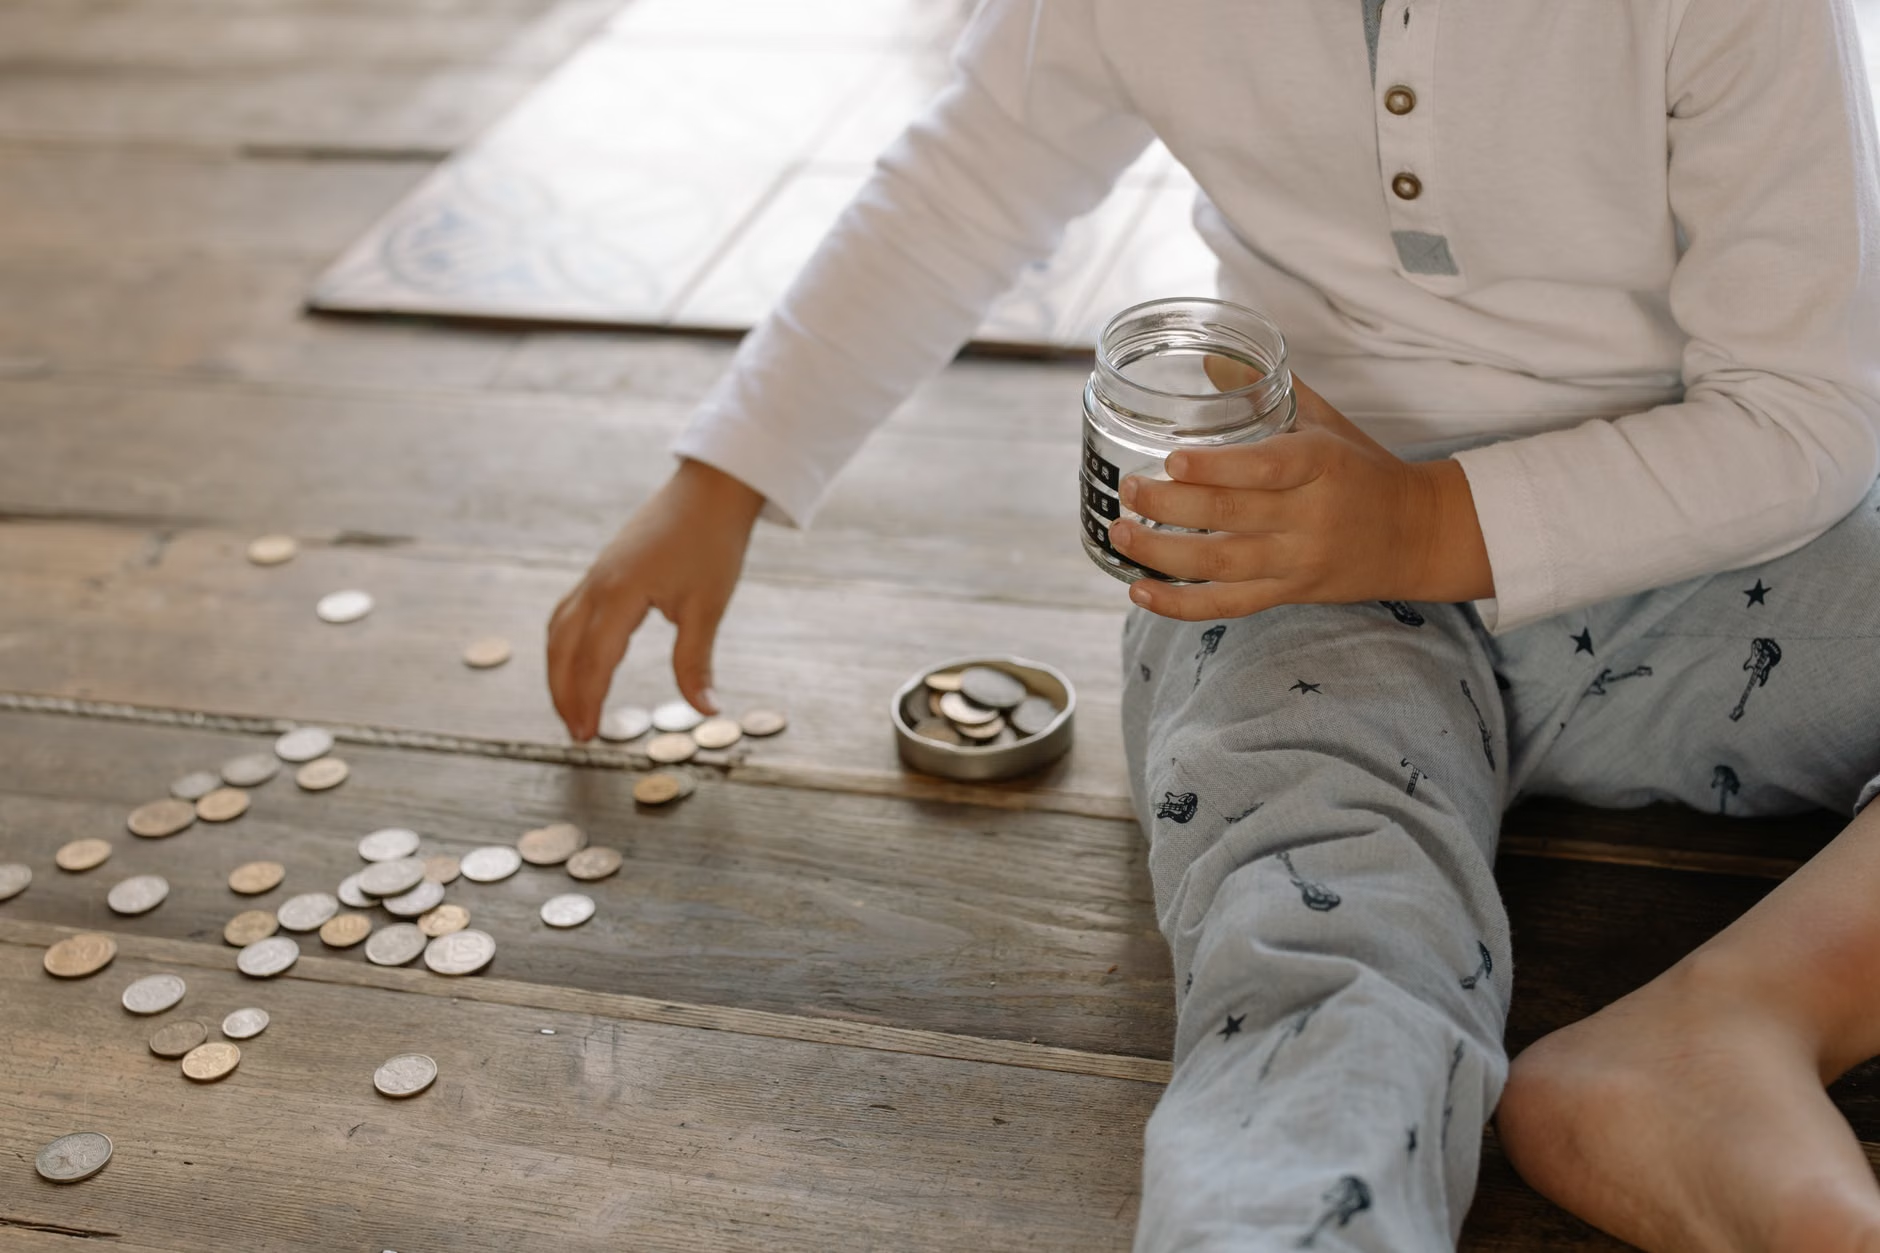
Once the money is earned, the next hurdle is ensuring it isn’t immediately squandered on impulsive, low-value purchases. This is where the 3-Jar System—or a digital equivalent using bank sub-accounts—becomes essential. For younger children, physical jars are highly effective because they make the abstract concept of money tangible.
The Spend Jar: This is for immediate needs or small desires. It allows the child to experience the “pain” of spending money, which is a critical part of financial education. If they run out of money here, they have to wait until the next allocation.
The Save Jar: This is for medium-to-long-term goals. This teaches delayed gratification. If they want a new video game or a high-quality piece of sports equipment, they must track their progress toward that specific number. You can even act as the “Bank of Mom and Dad,” offering a small interest rate if they keep the money in the jar for a certain period, teaching them the power of compound interest in a way they can actually see.
The Give Jar: This is for charitable contributions or helping others. This teaches empathy and the idea that money has a social utility beyond personal consumption. It prevents the child from becoming overly self-centered in their financial outlook.
Common Mistakes Parents Make
One of the most frequent errors is “bailout culture.” If your child spends their “Spend” money on something frivolous and then cries because they don’t have enough for a school trip or a desired toy, it is tempting to provide “emergency funding.” Resist this urge. The primary lesson of an allowance system is that resources are finite. If you provide a bailout, you destroy the entire incentive structure.
Another common mistake is changing the rules mid-stream. If you agree to a payment structure for a growth task, you must honor it, even if you realize later that it was “too easy” for them. Use that as a data point for your next negotiation, but do not punish the child for your own lack of foresight. This builds trust, which is the bedrock of the entire system.
Finally, avoid comparing your child’s financial habits to those of their peers. Your child’s allowance is a private, developmental tool, not a social status symbol. Keep the discussions about their goals and their progress, not about what “everyone else” is getting.
Scaling the System from Age 7 to 17
The system needs to evolve as your child grows. A seven-year-old needs physical jars and simple tasks like “learning to fold laundry perfectly.” A fourteen-year-old, however, should be managing a digital budget and perhaps taking on more complex tasks, such as managing a household inventory or helping with meal planning for the week.
As they enter their teenage years, you might consider moving from a “task-based” payment to a “budget-based” stipend. In this model, you calculate the average cost of their needs (toiletries, entertainment, hobby supplies, school lunches) and provide that as a set monthly amount. They are then responsible for managing that budget. If they overspend, they have to find ways to earn more or cut costs. This is the ultimate test of their financial maturity before they head out into the real world.
The Hidden Power of ‘Budgetary Autonomy’
The true value of this system isn’t the money itself, but the autonomy it grants the child. When a child has to make decisions about how to allocate their own funds, they are forced to confront trade-offs. They learn that every purchase is an opportunity cost. If they spend money on a cheap toy today, they are sacrificing the ability to buy a higher-quality, more durable item in the future.
This is a lesson that many adults struggle with. By starting in childhood, you allow them to make these mistakes when the stakes are low. A ten-year-old losing $10 on a bad purchase is a valuable lesson; a thirty-year-old losing $10,000 on a bad investment is a catastrophe. Use the allowance system as a “sandbox” for financial decision-making.
Developing the ‘Growth-Mindset’ Mindset
To truly embed a growth mindset, you must shift your language as a parent. Avoid saying, “You are so good with money.” Instead, say, “I noticed how you researched the price of that item before deciding to buy it; that was a very smart planning strategy.” Focus on the strategy and the effort, not the inherent trait.
When they fail—and they will—use it as a coaching moment. Ask them, “What did you learn from this? If you had to do it again, what would you change?” This keeps the conversation focused on improvement rather than failure. The allowance is just the vehicle; the conversation is the destination.
It is also crucial to involve them in the broader family finances where appropriate. Show them the utility bills or the grocery budget. Let them see how you, as an adult, manage your own resources. When they see you making trade-offs—choosing to cook at home to save for a family vacation, for example—they learn that financial management is a lifestyle, not just a chore.
Addressing Potential Hurdles
What if your child loses interest? This is normal. The novelty of the system will wear off. When this happens, revisit the “Growth Tasks.” Perhaps the tasks have become too routine. Engage them in a brainstorm session: “What is something you want to learn or do this month that we could turn into a growth project?”
What if they become obsessed with money? If your child starts focusing only on the “earning” and forgets the “giving” or the “learning,” pull back. Remind them that the goal of the system is personal development, not wealth accumulation. Rebalance the jars if necessary. The “Give” jar is your best tool here; if they are becoming too focused on themselves, suggest a project where the “Give” jar can have a direct, visible impact, such as buying supplies for an animal shelter or contributing to a local community garden.
Finally, be patient. This is not a short-term fix. It is a multi-year curriculum. You are building habits that will last a lifetime. There will be days when the system feels like more work for you than for them, but the long-term payoff of having a child who understands the value of effort, planning, and delayed gratification is worth every moment of effort you invest now.
Ultimately, the growth-mindset allowance system is about empowering your child to become a self-reliant individual. It shifts the power dynamic from “parent-as-provider” to “parent-as-mentor.” By giving them the tools, the structure, and the freedom to succeed and fail in a controlled environment, you are preparing them for the complexities of adult life in a way that mere lectures on “saving money” never could.
Frequently Asked Questions
1. At what age should I start the growth-mindset allowance system?
Most children are ready to grasp the basic concepts of the 3-jar system around age 6 or 7. At this age, they are beginning to understand simple math and the idea that money can be exchanged for goods. Start small, keep the tasks simple, and focus on the habit of sorting the money rather than the amount itself.
2. Should I pay for grades?
Generally, no. Paying for grades can shift a child’s focus from the joy of learning to the reward of the grade itself, which is the antithesis of a growth mindset. Instead, consider paying for the “process” of studying—such as creating a study schedule, researching a difficult topic, or spending extra time with a tutor. This rewards the effort and the strategy, which are within the child’s control, rather than the grade, which is an outcome.
3. What if my child refuses to do their core contributions?
Core contributions should be non-negotiable as they are part of being a functioning family member. If your child refuses, frame it as a loss of privilege rather than a loss of pay. For example, if they don’t do their part to set the table, the family cannot sit down to eat, which means their screen time or leisure time is delayed. Keep the focus on the natural consequences of their actions rather than using money as a bribe or a punishment.
For further reading on building financial habits in children, you can consult resources from the Consumer Financial Protection Bureau’s “Money as You Grow” initiative, which provides age-appropriate milestones for financial literacy.