If you own a waterfront home or are dreaming of buying one, the “Blue Economy” is no longer just a buzzword used at climate summits—it is rapidly becoming a primary factor in how your local government calculates your property taxes and insurance premiums.
- Tax Re-assessments: Municipalities are shifting from simple property valuation to “resilience-adjusted” taxing, where properties with natural shoreline protections may soon qualify for lower tax rates than those relying on aging, high-maintenance seawalls.
- The Insurance-Tax Nexus: As climate risk models become more sophisticated, the “Blue Economy” focus on restoring coastal ecosystems is directly lowering municipal disaster-mitigation costs, which in turn stabilizes property tax hikes that were previously used to fund emergency infrastructure.
- Value Shift: Future resale value will be increasingly tied to “Blue certification”—properties that contribute to, rather than degrade, the marine environment will likely see higher appreciation as regulatory pressure on coastal development intensifies.
You’ve likely seen the headlines about rising sea levels and the increasing frequency of storm surges. For those of us in our 30s and 40s, balancing mortgage payments, school fees, and the desire to live near the water, the math is changing. We are no longer just paying for the view; we are paying for the privilege of being part of a fragile ecosystem that governments are now rushing to protect.
What is the ‘Blue Economy’ and Why Does it Hit Your Wallet?
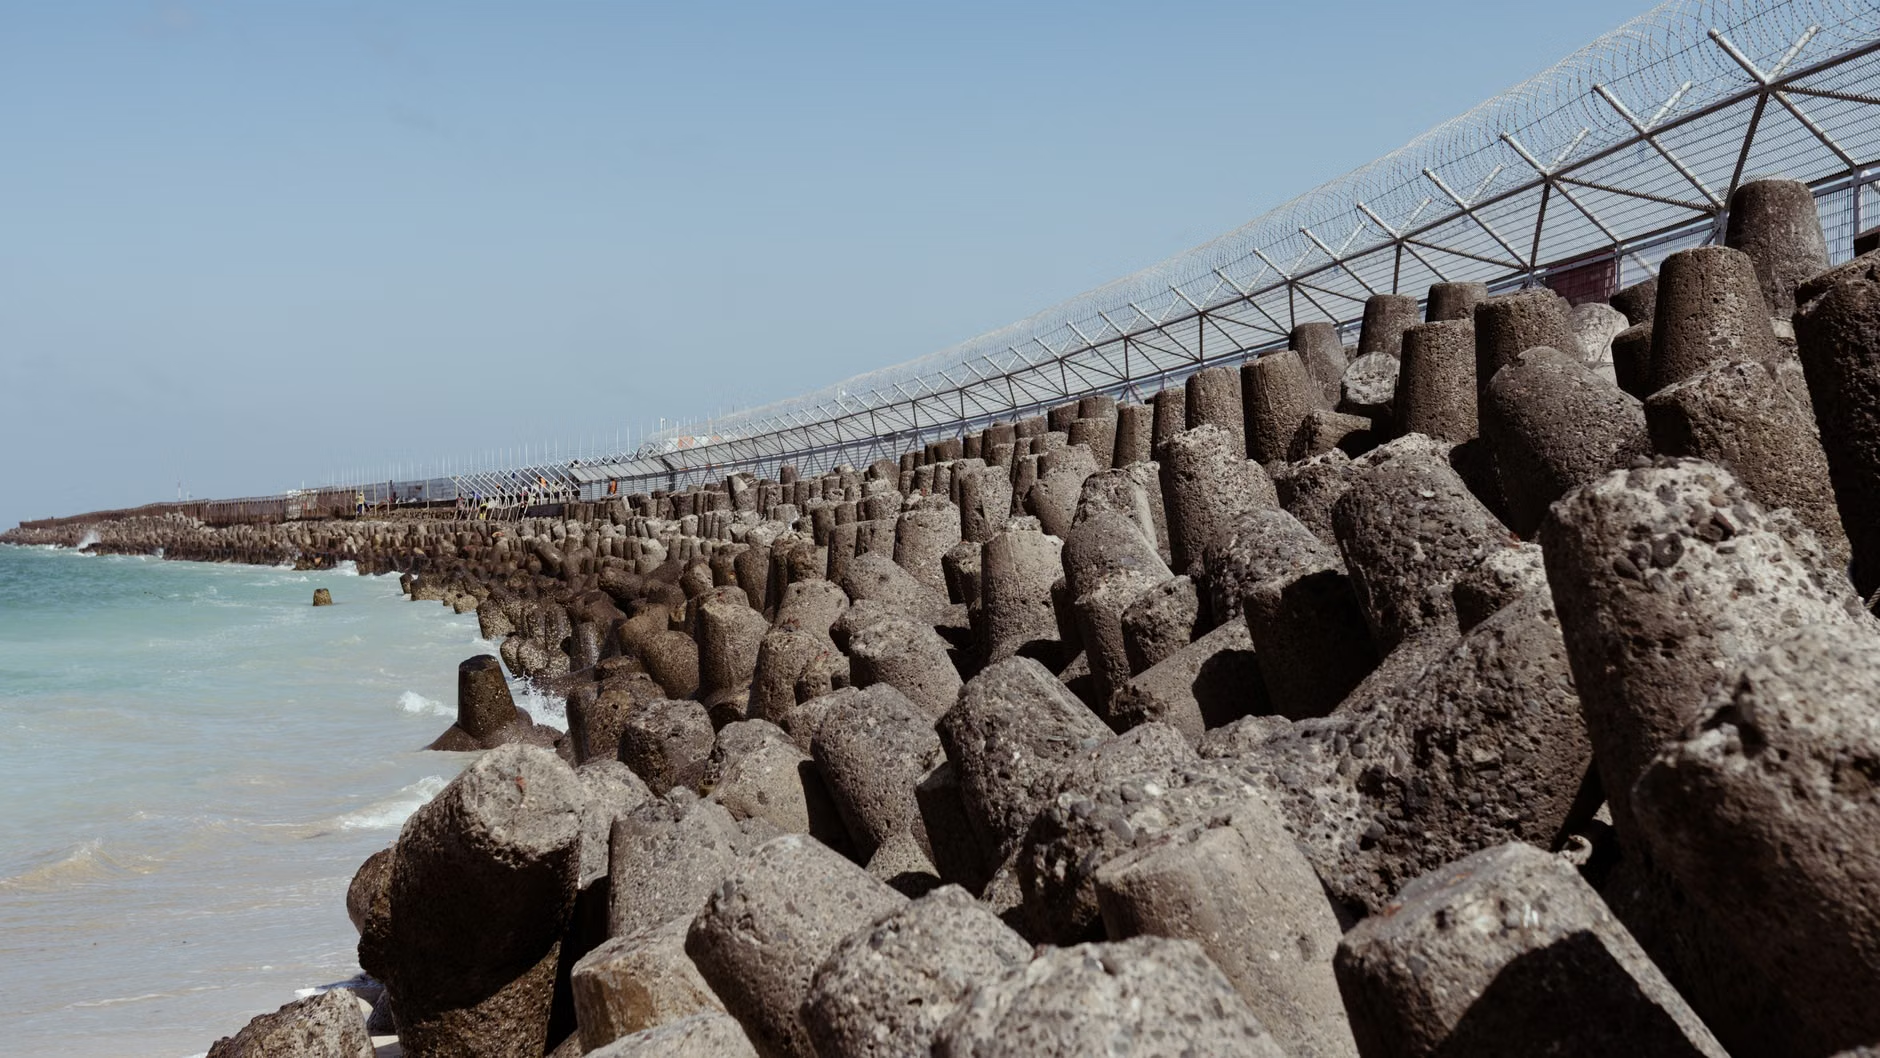
In the simplest terms, the Blue Economy is the sustainable use of ocean resources for economic growth, improved livelihoods, and ocean ecosystem health. Historically, waterfront development followed a “grey” model: concrete seawalls, dredging, and land reclamation. These methods were cheap to build but incredibly expensive to maintain and environmentally destructive.
Governments are now pivoting toward “Blue” infrastructure: restoring salt marshes, mangroves, and seagrass beds to act as natural buffers against waves and storm surges. This isn’t just an environmental initiative; it is a hard-nosed financial strategy. A healthy mangrove forest provides the same storm protection as a multi-million dollar breakwater, but it doesn’t require constant, tax-funded repairs.
For you as a homeowner, this means your local tax authority is likely beginning to differentiate between properties that support these natural systems and those that actively degrade them. If your property is contributing to coastal erosion, expect to see “environmental impact fees” or higher property tax assessments in the coming decade as municipalities shift the burden of ecosystem services onto those directly benefiting from the waterfront.
The Shift in Property Tax Assessment Models
Traditionally, property taxes were calculated based on square footage, location, and recent sales of comparable homes. This archaic model is failing to account for the massive, hidden liabilities of coastal living. We are entering an era of “Risk-Adjusted Property Valuation.”
Think of it like car insurance. If you have a high-performance vehicle with a history of accidents, your premiums spike. Waterfront homes are currently being re-evaluated through the same lens. Municipalities are using high-resolution satellite imagery and LIDAR (laser scanning) to assess the “resilience score” of your property. If your home sits on a hard, non-porous surface that increases runoff and erosion, your property might be flagged as a higher risk to the local infrastructure, leading to a higher tax burden.
How Resilience Scores Impact Your Annual Bill
To understand how this might look in your local jurisdiction, consider the following comparison of two hypothetical homes in the same coastal district:
| Feature | Standard Waterfront Home | Blue-Certified Waterfront Home |
|---|---|---|
| Shoreline Type | Concrete Seawall | Living Shoreline (Native Plants) |
| Drainage | Direct Runoff (Impermeable) | Bioswales and Permeable Pavers |
| Tax Treatment | High-risk surcharge applied | Resilience tax credit applied |
| Maintenance | High (Constant repair) | Low (Self-sustaining) |
This isn’t theoretical. Regions like the Florida coast, parts of Australia, and the UK are already experimenting with tiered tax structures. If you are shopping for a home, you must look beyond the kitchen finishes. You need to ask about the “coastal development permit” history and whether the current shoreline protection is considered an asset or a liability by the local planning department.
The Hidden Link Between Your Taxes and Insurance Premiums
One of the most overlooked aspects of the Blue Economy for homeowners is the intersection of local taxes and private insurance. In many coastal regions, when a major storm hits, the local government is responsible for cleaning up, repairing public roads, and restoring damaged coastal infrastructure. This is almost always funded by property taxes.
When a neighborhood is designed with “Blue” principles, the natural environment absorbs the energy of the storm. This means less damage to public roads and sewage systems, which keeps your municipal tax bill stable. Conversely, in areas with extensive concrete hardening, the water is deflected rather than absorbed, causing more damage to surrounding public assets during surge events. Taxpayers in those areas are essentially subsidizing the failure of hard infrastructure.
As a homeowner, you need to understand that your property tax bill is essentially a proxy for your share of the town’s climate risk. If your neighborhood has invested in the Blue Economy, you are likely looking at more predictable tax hikes. If your neighborhood is fighting the ocean with outdated, failing concrete walls, you are sitting on a ticking financial time bomb of special tax assessments.
What Should You Do Today?
If you own or are planning to buy a waterfront home, you need to stop thinking like a real estate speculator and start thinking like a coastal engineer. Here are the actionable steps you should take:
- Audit Your Shoreline: Is your property protected by a hard wall? If so, start researching “Living Shoreline” conversions. Many local governments now offer grants or tax rebates for homeowners who remove concrete seawalls and replace them with native, erosion-resistant vegetation.
- Check Your Local Hazard Maps: Don’t rely on the seller’s disclosure. Go to your local government’s GIS (Geographic Information System) portal. Look for “storm surge zones” and “erosion hazard areas.” If your property is in a high-risk zone, realize that your tax burden is likely to increase as the municipality shifts to “user-pays” models for coastal defense.
- Review Your Insurance Policy Against Local Mitigation: Does your insurance company provide discounts for properties that utilize natural disaster mitigation? Many insurers are beginning to offer “resilience discounts” for homes that meet specific environmental criteria.
The transition to a Blue Economy is not just about saving the planet; it is about the fundamental restructuring of how we value coastal land. The days of “build anywhere, pave everything” are coming to an end. The properties that will retain their value—and keep their tax bills manageable—are those that work in harmony with the sea, not against it.
Understanding the Long-Term Financial Implications
Many homeowners in their 30s and 40s are currently focused on short-term mortgage interest rates. While those are certainly important, the long-term volatility of coastal taxes could dwarf your interest rate changes over a 20-year horizon. We are seeing a trend where municipalities are beginning to issue “Climate Resilience Bonds” to fund large-scale coastal restoration. The debt service for these bonds is often passed down through property tax levies.
If you live in a district that is aggressively funding these projects, your property taxes will almost certainly rise. However, this is actually a positive sign. It means the local government is taking active steps to protect the asset value of your home. A town that ignores the Blue Economy will eventually face a catastrophic decline in property values when the insurance market decides the area is uninsurable or the infrastructure collapses entirely.
Therefore, when you see a line item on your tax bill for “Coastal Defense” or “Environmental Infrastructure,” don’t automatically view it as a negative. View it as a maintenance fee for your most valuable asset. The real danger is the town that has no such line item, as it suggests they are either ignoring the risk or waiting for a disaster to force their hand.
Common Misconceptions About Waterfront Living
There is a persistent myth that “the government will always bail out homeowners.” While this may have been true in the 20th century, the current fiscal reality is very different. FEMA and other national insurance programs are moving toward actuarial pricing—meaning the price you pay for protection will reflect the actual, un-subsidized risk of your property.
Another misconception is that “the seawall protects me, so I’m safe.” In reality, seawalls often cause “scouring,” where the energy of the wave is reflected downward, eating away at the base of the wall and the soil underneath. This makes your property *more* vulnerable to sudden collapse over time. A living shoreline doesn’t have this problem; it grows and strengthens over time, providing better protection as it matures.
Frequently Asked Questions
1. Will removing my seawall lower my property value?
While some buyers still associate “concrete” with “security,” the market is shifting. Modern buyers, especially those in the 30-45 demographic, are increasingly aware of maintenance costs and environmental risk. A well-designed living shoreline is increasingly being marketed as a premium, sustainable feature that reduces long-term insurance and maintenance costs, effectively increasing the property’s desirability.
2. Can I get a tax credit for making my property more resilient?
It depends on your local municipality, but many coastal regions are introducing “resilience incentives.” Check your local county or city website under “Environmental Planning” or “Coastal Management.” These programs often provide direct rebates, property tax abatements, or low-interest loans for homeowners who replace hardened structures with natural buffers.
3. How do I know if my property is at risk of future tax hikes?
Look for local government master plans regarding “Coastal Adaptation” or “Sea Level Rise Mitigation.” If your area has a published plan that involves significant public investment in infrastructure, you can expect property taxes to rise to fund those projects. If they don’t have a plan, your risk is actually higher, as the inevitable costs of future climate impacts will likely be passed on to you as emergency, rather than planned, expenses.
For further reading on how your region is adapting, you can check the official resources from the NOAA Blue Economy initiative or your local government’s environmental planning department. Taking the time to understand these macro-level shifts now will save you thousands of dollars and significant stress in the years to come.
Living by the water is a unique experience that provides a quality of life few other locations can match. By staying informed about the Blue Economy, you ensure that your home remains a source of joy rather than a source of financial anxiety. Start by looking at your own shoreline—the best time to adapt is before the next storm season arrives.